Venmo

- 340.13K Reviews
- 4.1
- Downloads
- 50,000,000+
 Analysis by Mobxio
If you’ve ever needed to split a dinner bill or pitch in for a group gift, you’ve probably heard of Venmo. This app has become a go-to for many when it comes to handling peer-to-peer payments. So, I decided to dive into the world of Venmo and see what all the fuss is about. Let me tell you, it’s quite the experience!
Free to start, with the right expectations
Venmo is a free finance app from Venmo, and that makes it easy to try as a way to handle everyday payments between people. Free access is a useful starting point, but I wouldn’t treat that alone as proof that every possible transaction is free. Before moving money, I’d check the details shown in the app for the specific action I’m taking and distinguish the basic cost of getting the app from any costs that might apply to a particular payment or transfer.
That distinction matters because a payment app can sit between several different choices: paying someone directly, using a linked funding source, keeping money in an app balance, or moving funds back to a bank. Those actions can have different terms. I’d avoid assuming that one experience tells me the cost of another, and I would read any confirmation screen carefully before approving a transfer. The practical takeaway is simple: the app itself is free to access, while I’d make transaction decisions based on the terms displayed for that transaction.
Where the convenience actually pays off
The biggest value for me is not that Venmo replaces every banking task. It is that it can reduce the awkward back-and-forth around small shared expenses. When a friend buys the group’s lunch, a roommate covers a household item, or several people contribute to a present, one clear request can be easier to track than a chain of messages about who owes what. For those situations, the convenience is real: people can settle up without needing to coordinate a cash handoff.
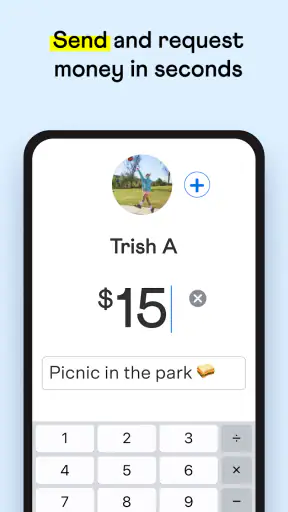
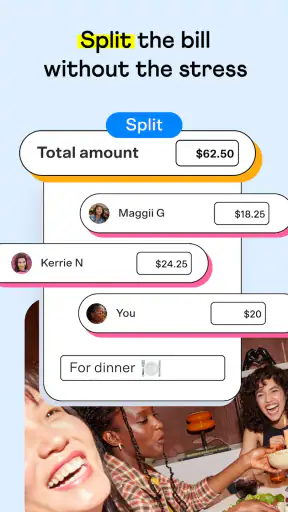
A realistic example is a shared dinner where one person pays the bill. Instead of trying to calculate everyone’s share while the group is still at the table, I can agree on what I owe and send it after the meal. A short note helps both people recognize the payment later. For a group gift, the organizer can request contributions individually, which can make it clearer who has responded and who still needs a reminder. I’d still confirm the amount with the recipient rather than rely on a vague description, especially if several payments are happening at once.
The app is also more useful when the people I deal with already use it. Peer payments depend on both sides being comfortable with the same service. If a friend does not have an account or would rather use another method, Venmo may add a step rather than remove one. In my view, its value grows through shared use: it is most convenient as a common option among friends, roommates, and family, not as a universal way to pay anyone.
What using Venmo is like in practice
I find Venmo most useful when a payment is part of an ongoing conversation between people who already know one another: splitting a meal, collecting for a shared purchase, or settling a small household expense. In this section, I’d focus on the practical choices that keep those exchanges clear, especially checking the recipient, amount, and privacy settings before sending. That everyday workflow also helps explain where its convenience has limits.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
Easy Peasy Setup
Getting started with Venmo is a breeze. You just download the app, sign up with your email or Facebook account, and you’re good to go. Linking your bank account or card is straightforward, and the app guides you through each step. I found the whole process refreshingly simple, even for someone who isn’t exactly tech-savvy.
Sending and Receiving Money
Once you’re all set up, sending and receiving money is as simple as sending a text. Just tap on “Pay or Request,” enter the amount, and off it goes. I was impressed by how quickly transactions are processed. Whether you’re paying your share of the rent or chipping in for a friend’s birthday present, Venmo makes the process seamless.
A small workflow that prevents mix-ups
For a payment to the right person, I’d take a moment to check the recipient before tapping send, especially when names are familiar or a group is involved. I’d also put a plain, recognizable note on each payment. That makes it easier to understand the activity later without turning the note into a place for sensitive details. If I’m collecting several contributions, I’d keep a separate list of expected amounts rather than assume the payment feed alone is a complete record of the plan.
Requests are particularly handy when I am the person who paid upfront. Instead of sending a string of individual reminders, I can ask each person for their share. The trade-off is that a request is still a social interaction: people may overlook it, disagree with the amount, or prefer to settle another way. I find a brief message explaining what the request covers is more considerate than sending an unexplained prompt, and it lowers the chance of someone mistaking it for a duplicate or an unexpected charge.
Social Vibes
One of the unique features of Venmo is its social feed. You can see who’s paying whom and even add comments or emojis. It’s like a social media platform for your finances. I found it fun to see quirky notes people left for each other, but if you’re a private person, you can easily adjust the settings to make transactions private.
The social element is a genuine point of difference from a conventional bank transfer, but it is also the part I’d approach most thoughtfully. A payment note does not need to explain the whole story; a short, neutral label is usually enough to help the people involved. I would review the privacy choices rather than assume my preferred setting is already selected, and I’d ask friends not to include personal context in public-facing notes. That is a more useful habit than treating every transaction like a status update.
Security and Privacy
Now, let’s talk about security. Venmo uses encryption to protect your financial information, which is reassuring. However, I’d recommend setting up a PIN code or enabling fingerprint authentication for an extra layer of security. It’s always better to be safe than sorry, right?
I’d also make it a routine to pause before confirming a payment. Peer-to-peer payments are designed to be direct, so checking the recipient and amount beforehand is more practical than assuming a mistaken send will be easy to reverse. If a request seems unfamiliar, I’d contact the person through a channel I already trust before paying it. These habits do not make the app harder to use; they help me keep the convenience without becoming careless around money.
Funding choices and the bank-transfer question
People often want to know whether an app like this can replace their bank account. I wouldn’t use Venmo as a substitute for a bank’s full set of services. Its strongest role here is handling person-to-person payments and certain purchases, while ordinary banking needs are better handled through the bank or financial provider that already manages those needs. I’d keep an eye on which funding source I select and verify the details before sending, rather than treating all payment methods as interchangeable.
Receiving money and moving it onward are also separate steps in a real workflow. If I need funds in my bank account, I would check the transfer choices and timing presented in the app before relying on the money for a deadline. That is especially important for rent, a bill, or any payment where the date matters. The app can make settling with another person convenient, but I would not assume that a balance transfer and a peer payment happen on the same schedule.
Additional Features
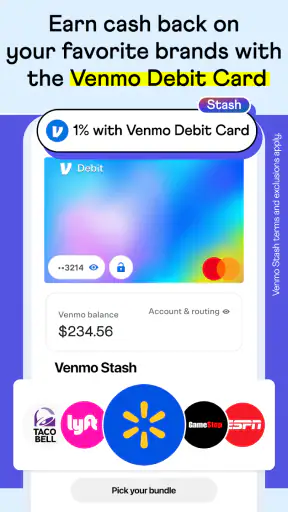
Venmo isn’t just about splitting bills. You can also use it to pay for purchases at select stores, which is pretty convenient. And if you ever run low on funds, you can transfer money from your Venmo balance back to your bank account. I found these features handy, especially when I needed quick access to cash.
Paying at select stores can make the app useful beyond splitting expenses, though I would not plan a shopping routine around it without checking whether a particular merchant accepts it. That is the key limitation of a selective payment option: it can be convenient when available, but it does not have the universal reach of carrying a broadly accepted payment card. For a purchase where acceptance is uncertain, I’d have another payment method ready rather than count on Venmo working everywhere.
How it compares with familiar alternatives
Compared with cash, Venmo can spare people the need to have exact bills or arrange a later handoff. Compared with a bank transfer, it can feel more tailored to casual payments between people who already share the app, with requests and payment notes making the exchange easier to identify. A bank remains the more natural choice when I need to manage a broader financial relationship or follow the process my recipient already uses. Neither option wins in every situation; the best one is the method both people can use comfortably and understand clearly.
Compared with other peer-payment apps, the deciding factor is often not a list of features but whether my friends and family are already there and what terms apply to the transaction I need. I would not ask someone to install another service just to pay me a small amount if they have a simpler option they trust. For recurring shared expenses, though, having a familiar place to send requests can reduce friction. Venmo is a practical fit when the social circle has adopted it, not an automatic upgrade over every alternative.
Who gets the most from it—and who may not
I’d recommend Venmo to someone who regularly divides meals, shared household costs, or group purchases with people who are comfortable using it. It can also suit a person who likes seeing a clear record of casual payments and requests in one place. The app has a 4.1 average from around 871,000 ratings, and it has passed 50 million installs, which suggests many people have made it part of their payment routine. It is free, rated for Everyone, and developed by Venmo; the current version is 10.78.1, with a minimum OS requirement of 8.0.
On the other hand, I’d skip it if I mainly need a full-service banking app, if my contacts use other payment methods, or if a social feed around payments feels uncomfortable even with privacy controls. It may also be the wrong tool when I need guaranteed acceptance at a store or a transfer to arrive by a specific deadline. In those cases, a bank’s own service, cash, or another method accepted by the recipient can be a better match. Choosing a different tool is not a failure; it is simply more reliable than forcing every payment into one app.
Worth trying, with sensible boundaries
Venmo has been around since May 17, 2010, and its appeal is easiest to understand in ordinary moments: a friend covered the meal, a roommate bought something for the home, or a group is pooling money for a gift. It makes those exchanges feel less cumbersome when everyone involved is on board. I like that practical role, but I would keep expectations focused on casual payments rather than treating it as a replacement for every financial tool.
My advice is to set up privacy and device-security choices thoughtfully, use clear but non-sensitive payment notes, and check recipient, amount, funding source, and transfer terms each time they matter. Those small habits address the main points where convenience can turn into confusion. If the people I pay already use Venmo and I want a straightforward way to settle shared costs, I’d give it a try. If they do not, or if I need broader banking features or dependable acceptance in more places, I’d choose the method that better fits that job.
Overall, Venmo has carved out a niche for itself in the world of digital payments. It’s user-friendly, fast, and a bit of fun with its social aspect. Whether you’re a college student or a busy professional, Venmo can make managing your finances a little less daunting. Give it a try and see how it fits into your life!
Venmo FAQ
What is Venmo and how does it work?
Venmo is a mobile payment service that allows users to transfer money to one another using a mobile app, which is available on both Android and iOS. It's linked to your bank account or credit card and is used for splitting bills, paying friends, or making small purchases. The app provides a social feed showing your transactions, making it unique among payment services.
Is Venmo safe to use for transactions?
Venmo employs encryption and security measures to protect user data and financial information. It offers multi-factor authentication and allows users to set PIN codes for additional security. However, users should be cautious and avoid using Venmo for transactions with strangers, as it is designed for exchanges between people who trust each other.
Are there any fees associated with using Venmo?
Venmo is generally free to use for sending money from a linked bank account, debit card, or Venmo balance. However, a 3% fee applies when sending money using a credit card. Instant transfers to your bank account typically incur a 1.5% fee, with a minimum fee of $0.25 and a maximum fee of $15.
Can I use Venmo for business transactions?
Venmo is primarily designed for personal transactions, but it does offer options for businesses. Businesses can apply for a Venmo business profile to accept payments, which incurs a standard fee of 1.9% + $0.10 per transaction. It's important for businesses to comply with Venmo's policies and ensure they have the appropriate setup.
What are the social features of Venmo?
Venmo offers a social feed where users can share their payment activities with friends. Users can like and comment on transactions, adding a social element to the payment process. Privacy settings allow users to control who can see their transactions, whether it be the public, friends, or only the people involved in the transaction.
The Best Parts of Venmo
Things to Keep in Mind About Venmo